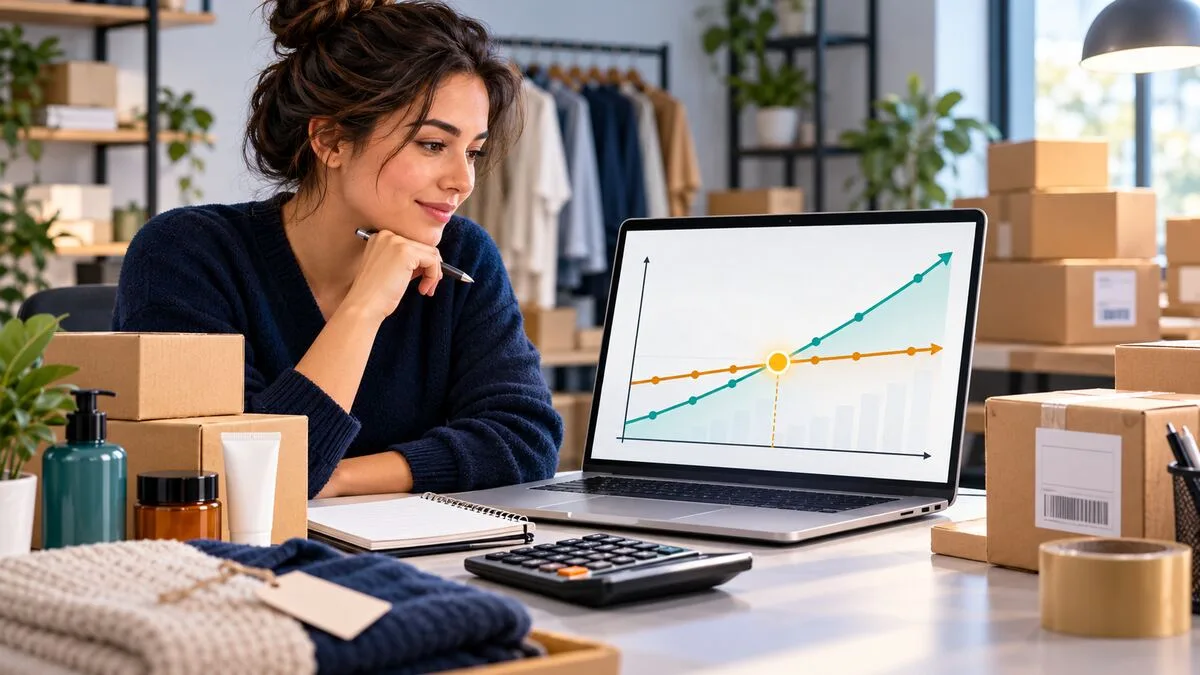
Your break-even point is the sales level where the money left after variable costs exactly covers your fixed costs. At that point, the business has made neither a profit nor a loss. For an online seller, knowing this number turns a vague monthly sales target into a practical answer: how many orders—or how much revenue—must you generate before you start earning profit?
Break-even point formula for online sellers
For a store that sells one main product, use:
Break-even units = fixed costs ÷ contribution margin per unit
Your contribution margin per unit is:
Contribution margin = selling price − variable cost per unit
Variable costs are expenses that increase when you make a sale. Fixed costs are expenses you must pay even if no orders arrive.
You can check your numbers quickly with the Break-Even Units Calculator.
A simple break-even example
Suppose you sell a product for $40. Each sale has these variable costs:
- Product cost: $14
- Marketplace and payment fees: $5
- Packaging: $1
- Shipping subsidy paid by your store: $4
- Average advertising cost per order: $3
Total variable cost is $27, so the contribution margin is $13 per sale. If your monthly fixed costs are $1,950:
$1,950 ÷ $13 = 150 units
You must sell 150 units in that month to break even. Unit 151 begins contributing to operating profit, provided the assumptions remain accurate.
What counts as a fixed cost?
Fixed costs do not usually change in direct proportion to each order. Common examples include:
- Store or marketplace subscription plans
- Accounting, bookkeeping and business software
- Warehouse, studio or office rent
- Base payroll and contractor retainers
- Insurance, licences and recurring professional fees
- Equipment depreciation or lease payments
- A fixed monthly advertising retainer
Some costs are only fixed within a certain range. A warehouse may handle your current volume, but a second space could be required after growth. Review the calculation whenever the cost structure changes.
What counts as a variable cost?
Include every cost that is caused by, or closely follows, a sale:
- Inventory or manufacturing cost
- Marketplace commission and payment processing
- Pick-and-pack charges
- Packaging materials
- Postage or the portion of shipping you subsidise
- Affiliate commission
- Advertising cost per acquired order
- Expected return, refund and reshipment cost
Seller fees are easy to underestimate because some are percentages while others are charged per transaction. Use the relevant SellersNest marketplace calculator for the platform you sell on, then place the realistic fee amount in your break-even calculation.
Do not confuse contribution margin with profit margin
Contribution margin shows how much one sale contributes toward fixed costs and profit. Net profit is what remains after both variable and fixed costs have been covered.
If you want to compare your price, cost and profit percentage, use the Profit Margin Calculator. For the difference between markup and margin, see Markup vs Margin: The Difference That Quietly Costs Sellers Money.
How to calculate break-even revenue
If you sell many products, a revenue target can be more useful than one unit target. First calculate your contribution margin ratio:
Contribution margin ratio = contribution margin ÷ sales revenue
Then calculate:
Break-even revenue = fixed costs ÷ contribution margin ratio
If your store keeps $30 in contribution margin from every $100 of sales, the ratio is 30%. With monthly fixed costs of $6,000, break-even revenue is:
$6,000 ÷ 0.30 = $20,000
This works best when your product mix and average margin are reasonably stable.
Break-even analysis for stores with multiple products
A store selling several products should use a weighted average contribution margin. Multiply each product’s contribution margin by its expected share of unit sales, then add the results.
For example, if Product A contributes $20 and represents 60% of sales, while Product B contributes $10 and represents 40%, the weighted contribution is:
($20 × 60%) + ($10 × 40%) = $16 per unit
If customer demand shifts toward the lower-margin product, your true break-even point rises. Recalculate using recent sales mix rather than assuming last year’s mix still applies.
Include advertising without double counting it
Advertising can be treated in two ways. A fixed monthly campaign budget can sit under fixed costs. Performance spending that varies with each order can be included as a variable acquisition cost.
Choose one method for each expense and do not enter the same cost in both places. If you track customer acquisition cost, compare it with the contribution available before advertising. The guide to customer acquisition cost for online sellers explains how to separate new-customer spending from general traffic costs.
Adjust for returns and refunds
Break-even calculations often look too optimistic because they treat every order as a completed sale. Estimate the average cost of returns, refunds, damaged goods, chargebacks and reshipping, then assign that expected cost across orders.
For example, if return-related losses average $300 across 100 orders, include $3 per order as an expected variable cost. Review your ecommerce return rate before relying on the final target.
How discounts change your break-even point
A discount reduces contribution margin unless costs fall at the same time. If the example product’s price drops from $40 to $36 while variable costs stay at $27, contribution margin falls from $13 to $9. With $1,950 in fixed costs, break-even volume rises from 150 units to about 217 units.
That means a 10% price cut requires roughly 45% more unit sales in this example just to reach the same break-even result. Test promotions with the Discount & Sale Price Calculator before launching them.
Add a target profit to the formula
Breaking even keeps the business alive, but it does not pay the owner a profit. To set a more useful target, add desired profit to fixed costs:
Required units = (fixed costs + target profit) ÷ contribution margin per unit
Using fixed costs of $1,950, a target profit of $2,000 and contribution of $13:
($1,950 + $2,000) ÷ $13 = about 304 units
This turns break-even analysis into a sales-planning tool rather than a survival-only measure.
Common break-even mistakes
- Using selling price instead of contribution margin in the formula
- Leaving marketplace fees, packaging or shipping subsidies out
- Ignoring refunds, chargebacks and damaged inventory
- Treating sales tax collected for the government as store revenue
- Using one average margin when the product mix changes sharply
- Forgetting the owner’s regular wage or required compensation
- Assuming a seasonal sales target should be identical every month
- Failing to update costs after supplier or carrier price changes
A practical monthly routine
- Update selling prices and product costs.
- Recalculate marketplace, payment and fulfilment fees.
- Measure average advertising and return cost per order.
- Total the fixed costs for the same period.
- Calculate break-even units and revenue.
- Compare the target with current conversion rate and order volume.
- Run a second scenario for a price increase, discount or cost change.
Keep a base case, a cautious case and an optimistic case. A range is more useful than pretending every future cost and order will match one exact forecast.
Final takeaway
The break-even point tells you the minimum sales performance your store needs before it creates profit. Use contribution margin—not revenue alone—include the less obvious costs attached to each order, and update the calculation whenever prices, fees, advertising or product mix changes. A realistic break-even target helps you price promotions, set sales goals and spot an unprofitable offer before it drains cash.