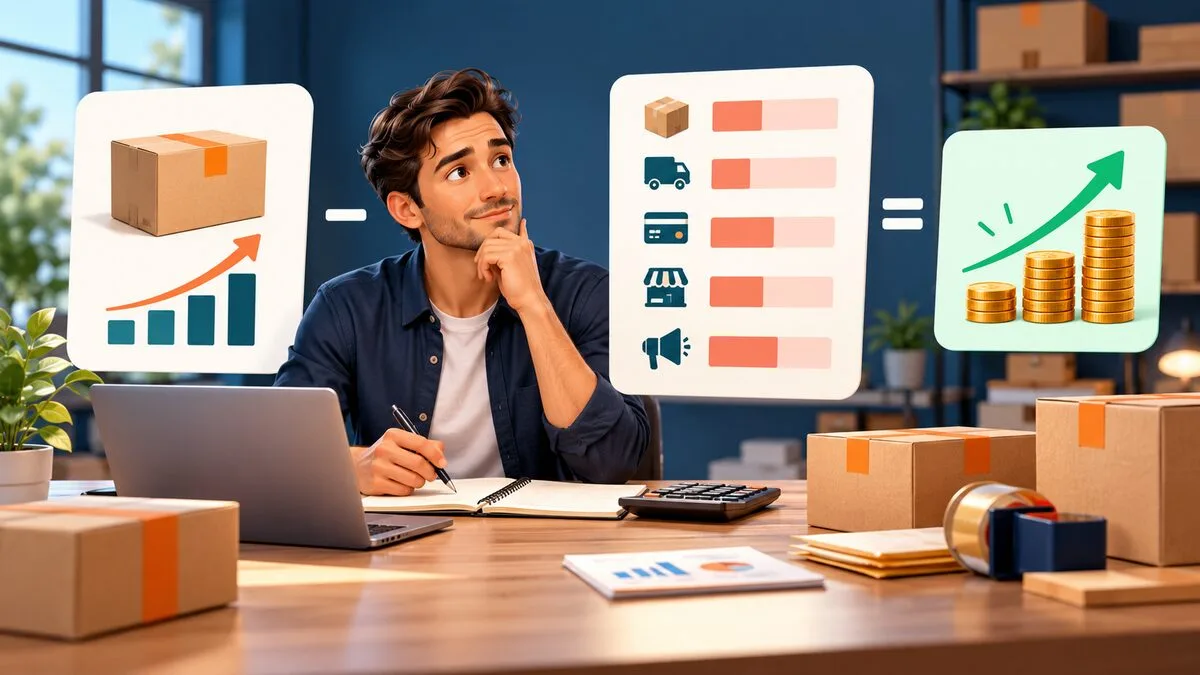
Contribution margin is the money left from a sale after paying the costs that rise when you sell that order. For online sellers, it shows whether each order contributes enough to cover fixed expenses and eventually produce profit.
Revenue can look healthy while contribution margin is weak. A product sold for $50 does not contribute $50 toward rent, software and owner pay. Product cost, marketplace fees, payment processing, packing, fulfilment, shipping subsidies, discounts, returns and order-level advertising may take most of it first.
What is contribution margin?
Contribution margin is sales revenue minus variable costs. Variable costs change with sales volume. Fixed costs—such as a base software subscription, warehouse rent or a monthly bookkeeping fee—usually remain similar whether you sell one order or 100.
Contribution margin = sales revenue − variable costs
You can calculate it per order, per product, per sales channel or for the whole business. Per-order contribution margin is usually the clearest starting point for ecommerce decisions.
Contribution margin versus gross profit
Gross profit normally subtracts cost of goods sold from revenue. Contribution margin goes further by subtracting other variable selling costs. The exact accounting treatment can vary, so define your method and use it consistently.
For example, payment fees, marketplace commission, pick-and-pack charges and outbound shipping may not appear in product cost, but they still reduce the money that an order contributes. Contribution margin makes those costs visible.
Net profit goes further again. It subtracts fixed operating expenses, taxes and other business costs from total contribution. If you only need to compare price, cost, markup and gross margin, use the free profit margin calculator.
Contribution margin formula for ecommerce
For one order:
Order contribution margin = order revenue − all variable order costs
Contribution margin percentage is:
Contribution margin ratio = contribution margin ÷ revenue × 100
Use net revenue after discounts and refunds. Be consistent about sales tax: if tax is collected for the government and is not your revenue, exclude it from both revenue and the related liability.
Worked example
Suppose an online seller receives a $75 order with these variable costs:
- product cost: $24;
- marketplace and payment fees: $9;
- packaging and fulfilment: $4;
- shipping paid by the seller: $8;
- order-level advertising cost: $7; and
- expected returns allowance: $3.
Total variable cost is $55. The order contribution margin is $75 − $55 = $20.
The contribution margin ratio is $20 ÷ $75 × 100 = 26.7%. That $20 must still help pay fixed costs before it becomes net profit.
Which ecommerce costs should you include?
Include a cost when it increases because the order happened. Common variable costs include:
- inventory or manufacturing cost;
- inbound freight and duty allocated per unit;
- marketplace commission;
- payment processing fees;
- pick-and-pack or fulfilment charges;
- packaging materials;
- outbound shipping paid by the seller;
- discounts and coupons;
- affiliate commission;
- order-level advertising cost;
- expected refunds, return shipping and write-offs; and
- royalties or per-sale software fees.
If imported inventory costs are incomplete, calculate the true unit cost first with the method in our landed cost guide. Oversized packaging can also change shipping economics; the dimensional weight calculator helps identify the billable weight carriers may use.
Do not mix fixed and variable costs
Monthly rent, annual insurance and fixed software plans usually belong below contribution margin. They matter for total profitability, but including them as arbitrary per-order costs can make product comparisons inconsistent.
Some costs are mixed. A fulfilment contract may include a fixed monthly minimum plus a charge per shipment. Separate the fixed part from the per-order part. Advertising can also be handled in two ways: include attributable ad spend when evaluating a campaign or exclude it when comparing the underlying product economics. Label the result clearly.
How contribution margin connects to break-even
Contribution margin tells you how much each unit contributes toward fixed costs. That makes it the key input for break-even analysis:
Break-even units = fixed costs ÷ contribution margin per unit
If monthly fixed costs are $4,000 and each order contributes $20, you need 200 similar orders to cover those fixed costs. The break-even calculator can test different prices and variable costs, while our break-even guide explains the full method.
What is a good contribution margin?
There is no universal percentage. A healthy result depends on fixed costs, order volume, return risk, cash flow and how much service the business must provide after purchase.
A low-margin product can still work at high volume with efficient operations. A high-margin product can still fail if demand is weak or fixed costs are excessive. Compare your margin with your own break-even requirement and test whether it remains positive after realistic fees, returns and acquisition costs.
Seven decisions contribution margin improves
1. Pricing
Test how a price change affects dollars contributed per order, not only the percentage margin. A lower price may increase volume but reduce the amount available to cover fixed costs.
2. Discounts
Discounts reduce revenue immediately while many costs stay unchanged. Before launching a sale, use the discount and sale price calculator and recalculate contribution margin at the promotional price.
3. Free shipping
Free shipping is not free to the seller. Compare the contribution from the current offer with a higher product price, a shipping threshold or a separate delivery charge.
4. Advertising limits
Contribution margin before advertising gives you an upper boundary, not a recommended budget. Spending the entire amount to acquire an order leaves nothing for fixed costs or profit. Compare it with the method in our customer acquisition cost guide.
5. Product mix
Rank products by contribution dollars as well as percentage. A product with a lower percentage may contribute more cash per order, while a high-percentage item may contribute very little in dollars.
6. Sales channels
Calculate contribution by marketplace, website and wholesale channel. Include channel-specific fees, advertising, fulfilment and return patterns. Revenue alone can hide an expensive channel.
7. Bundles and add-ons
A bundle can improve contribution when the extra product adds useful revenue without adding equal fulfilment and acquisition cost. Recalculate packaging, weight and discount effects before assuming the bundle is better.
Common contribution margin mistakes
- Using list price instead of actual revenue: account for discounts and refunds.
- Ignoring marketplace and payment fees: small percentages compound quickly.
- Leaving out shipping subsidies: customer-paid shipping may not cover the carrier cost.
- Using perfect return assumptions: allocate expected return costs using observed data.
- Counting all advertising the same way: separate attributable order spend from general brand activity.
- Comparing different definitions: document which costs are included.
- Focusing only on percentage: track contribution dollars per order and total contribution too.
A simple monthly contribution margin check
- Export completed orders, discounts and refunds.
- Calculate net revenue for each order.
- Attach product, fee, fulfilment, packaging and shipping costs.
- Add an expected return-cost allowance based on actual history.
- Calculate contribution dollars and percentage by order.
- Group results by product, channel, campaign and customer type.
- Compare total contribution with fixed operating costs.
- Investigate negative or unusually weak orders before changing prices.
Frequently asked questions
Is contribution margin the same as profit margin?
No. Contribution margin subtracts variable costs and shows what remains to cover fixed costs. Net profit margin includes fixed expenses and other business costs.
Should advertising be included?
Include attributable ad spend when evaluating a campaign or paid-acquisition order. You may also calculate a pre-ad contribution margin to compare products independently. Keep the two versions clearly labelled.
Can contribution margin be negative?
Yes. A negative contribution means the sale did not cover its variable costs. Increasing volume under the same conditions normally increases the loss.
Should owner labour be included?
Include labour that rises directly with each order if you want an operational contribution view. Fixed management time or owner salary is usually treated as a fixed operating cost. Consistency matters more than forcing every business into one template.
Bottom line: contribution margin shows what each ecommerce order really adds after variable costs. Calculate it in dollars and as a percentage, use conservative cost assumptions, and connect it to break-even before making decisions about price, discounts, shipping or advertising.